I'm here to discuss risk taking. R-squared is for Ranting and Raving, R&R, as well as some more technical topics
Sunday, October 29, 2017
Everything You Know About Taxing Retirement Saving Is WRONG!
Republicans have discussed eliminating pre-tax contributions to 401(k) plans as part of their massive tax overhaul. Everything you've read says this is a terrible result for you. But everything you've read is wrong. Here are five reasons...I cannot believe I am writing this...I agree with the GOP thought exercise that will never become reality...
Reason #1: Pre-tax savings forces difficult mental accounting, and allows you to delude yourself..
Deep down, you know this. The taxes are due at some point. How can you correctly plan for retirement when you are looking at total balances instead of after-tax distributions from that balance? This make a difficult long term planning problem worse. Tell me, what is your marginal tax rate going to be in 2040?
Reason #2: Pre-tax savings makes it easier for Congress to screw you in the future.
Are you really confident that your tax rate today is higher than your tax rate 20, 30 or 50 years from now? Congress can more easily raise taxes on income they have not yet taxed than income already taxed. This is why wealthy people are such fans of Roth conversions of their IRAs and 401(k)s.
Have you factored in inflation? What if inflation moves up in the next 40 years, and your real value of assets in that 401(k) haven't moved, but your distributions are way higher in nominal terms? Think that's crazy? Forty years of 6% inflation means you have 10x the dollars, but they buy you the same stuff. Think I'm crazy? A lot can happen in 40 years.
Reason #3: Deferring taxes benefits those finance folks you love to hate.
So, if you only really get $65,000 of future value from that $100,000 balance, who wins? Not the government, until they raise the future rate (reason #2...and they will do it!) Your mutual fund manager! She wins big. She collects management fees on the extra $35,000 that you give to her instead of the government. She's thrilled. You and your colleagues at work just built the new kitchen for her summer home.
Reason #4: Deferring taxes raises your tax rates.
This one is for the advanced reader. If you hold an equity index fund, the vast majority of your gains are capital gains, and they are deferred as long as you hold the investment. This is true of individual stocks as well. So, you basically don't pay taxes until you sell the investment, and then at reduced rates because it's a capital gain. On the flip side, when you hold long term equity assets in your 401(k), you are converting what would otherwise be capital gains into future ordinary income.
If you do some pretty simple calculations, you can show that owning equity index funds in a retirement plan actually destroys value versus holding the same investment in a taxable plan. You are holding assets that defer taxes forever at capital gains rates, but you then put them into a vehicle that makes them into ordinary income, taxed at an unknown, higher, future rate.
[Pro tip: Very wealthy people don't hold equities in retirement plans. They hold investments that generate ordinary income in retirement plans, and hold stocks in taxable accounts.]
Reason #5: Deferring taxes benefits the finance folks you don't like...even more!!
This one is for the even more advanced reader. So, you have your pre-tax 401(k) account. What to do with it? You look for a "good" portfolio manager, whatever that means to you. I can tell you if you aren't a professional, you are probably wrong in this decision. If you are a professional, you know your chances of being right are only slightly better than your changes of being wrong. If you're truly an expert, than you know a 401(k) can't be invested the way you want to invest.
You don't given a damn if your portfolio manager changes stocks like he changes socks. You aren't taxed on gains, and you don't distinguish between short term and long term. So, you have an incentive to seek out a manager who does "something" to add value over that passive index. That "doing something" costs you real money in higher fees over the long term, and maybe it adds value. (see reason #4 again...) And it keeps your fancy portfolio manager employed. Now, she's thanking you for the whole summer house, not just the new kitchen.
Wednesday, February 17, 2016
#EndingTBTF
The Federal Reserve Bank of Minneapolis seeks comments on how to end "Too Big To Fail".
A friend suggested I submit something, so maybe I'd be heard. So, here goes. I am simply submitting a link to this blog post:
I've written before how to do this conceptually, but here I'm giving slightly more detail:
Banks engage in two unrelated businesses:
TBTF status arises because banks currently face a mismatch between demand deposits and loans. You can't call all the loans to return cash to depositors. FDIC works for small, idiosyncratic risks of bank failures. Not giant or systematic ones. If we separate those activities, we shall see that the companies that accept demand deposits cannot fail and the companies that engage in lending fail to the detriment of their risk taking investors, not the public.
Three simple steps separate these activities:
First, Allow anyone to own a bank with 100% reserves.
Regulations today put severe restrictions on who can own banks. For the most part, non-financial companies cannot own banks. Regulators worried that bank deposits might end up supporting non-bank operations. Additionally, lending to competitors of the non-bank company might lead to anti-competitive behavior. (Imagine you made a loan to your competitor widget producer, and threatened to call the loan if they lowered their prices below yours.)
Now suppose you had a special class of bank that did not make loans. This bank held physical currency, Treasury securities and reserves as the Fed. This bank only deals in demand deposits and riskless securities. This bank cannot lend to companies or people. This bank cannot have a run.
This bank is not very profitable. This bank makes money on the spread between interest paid on reserves, Treasury securities and transaction fees. It might pay interest, depending on expenses. Who engages in this seemingly capital intensive, not very profitable business? Walmart, Target, Home Depot, Costco immediately start banks. They have stores full of tellers and cash. Currency is simply a product they already carry in their stores.
Second, Modify FDIC pricing
FDIC protects bank customers from bank runs. Because it protects bank customers, it protects bank shareholders. FDIC (and the risk of exceeding FDIC limits) are the source of TBTF. Bank customers treat bank deposits as riskless because they've been trained by FDIC to believe it. Corporate (and very wealthy) customers with deposits exceeding limits do not have a riskless alternative EXCEPT TBTF. If my company's payroll is $100 million a month, where do I put that cash so that it is absolutely safe?
New FDIC rules say banks with 100% reserves do not have to pay for FDIC insurance. Note: I'm not saying (right away) eliminate it. That would not be perceived well by the public. But, it's free. Because FDIC has no risk.
(Eventually, FDIC goes away. Or, maybe, since FDIC is much smaller than the industry of banking oversight in general, FDIC becomes the official organization that looks at a bank's balance sheet for about 10 minutes a quarter to say: Yup, you have no loans, and your cash plus Treasury securities plus reserves at the Fed equals your deposits. You're good to go!)
At the same time, ramp up FDIC insurance pricing quickly to banks with less than 100% reserves. Price increases will control the speed with which we separate demand deposit management from lending. FDIC transitions from an insurance handout encouraging TBTF to a painful tax on commingling demand deposits and lending.
What happens to the existing banks? They restructure into a banking subsidiary managing deposits and an investment manager running mutual funds, (because in the next step we kill money market funds!)
Third, eliminate money market fund pricing exemptions
Money market funds exist to deceive the public. I'm not overstating this in any way. If we remove the exemptions that allow money market funds to manipulate their net asset values so they look riskless, then the public will understand that bank deposits (in a 100% reserve bank) have no risk, but that money market fund's share price bounces around a little because it is risky. The money market fund is pretty darn available for withdrawal, but the price moves.
Under these circumstances, the saving and investing public makes clear distinctions between storing money in a way that is always available (saving), and lending money for risk taking purposes (investing.)
I suspect this third step would be the end of money market funds. Money market funds would become ultra short term bond funds...because that's what they are without the regulations designed to deceive us. At that point, however, there would be no reason NOT to let them fail. You, the investor took a risk. Too bad. You had an alternative.
A friend suggested I submit something, so maybe I'd be heard. So, here goes. I am simply submitting a link to this blog post:
I've written before how to do this conceptually, but here I'm giving slightly more detail:
Banks engage in two unrelated businesses:
- Banks make loans;
- Banks accept demand deposits.
TBTF status arises because banks currently face a mismatch between demand deposits and loans. You can't call all the loans to return cash to depositors. FDIC works for small, idiosyncratic risks of bank failures. Not giant or systematic ones. If we separate those activities, we shall see that the companies that accept demand deposits cannot fail and the companies that engage in lending fail to the detriment of their risk taking investors, not the public.
Three simple steps separate these activities:
First, Allow anyone to own a bank with 100% reserves.
Regulations today put severe restrictions on who can own banks. For the most part, non-financial companies cannot own banks. Regulators worried that bank deposits might end up supporting non-bank operations. Additionally, lending to competitors of the non-bank company might lead to anti-competitive behavior. (Imagine you made a loan to your competitor widget producer, and threatened to call the loan if they lowered their prices below yours.)
Now suppose you had a special class of bank that did not make loans. This bank held physical currency, Treasury securities and reserves as the Fed. This bank only deals in demand deposits and riskless securities. This bank cannot lend to companies or people. This bank cannot have a run.
This bank is not very profitable. This bank makes money on the spread between interest paid on reserves, Treasury securities and transaction fees. It might pay interest, depending on expenses. Who engages in this seemingly capital intensive, not very profitable business? Walmart, Target, Home Depot, Costco immediately start banks. They have stores full of tellers and cash. Currency is simply a product they already carry in their stores.
Second, Modify FDIC pricing
FDIC protects bank customers from bank runs. Because it protects bank customers, it protects bank shareholders. FDIC (and the risk of exceeding FDIC limits) are the source of TBTF. Bank customers treat bank deposits as riskless because they've been trained by FDIC to believe it. Corporate (and very wealthy) customers with deposits exceeding limits do not have a riskless alternative EXCEPT TBTF. If my company's payroll is $100 million a month, where do I put that cash so that it is absolutely safe?
New FDIC rules say banks with 100% reserves do not have to pay for FDIC insurance. Note: I'm not saying (right away) eliminate it. That would not be perceived well by the public. But, it's free. Because FDIC has no risk.
(Eventually, FDIC goes away. Or, maybe, since FDIC is much smaller than the industry of banking oversight in general, FDIC becomes the official organization that looks at a bank's balance sheet for about 10 minutes a quarter to say: Yup, you have no loans, and your cash plus Treasury securities plus reserves at the Fed equals your deposits. You're good to go!)
At the same time, ramp up FDIC insurance pricing quickly to banks with less than 100% reserves. Price increases will control the speed with which we separate demand deposit management from lending. FDIC transitions from an insurance handout encouraging TBTF to a painful tax on commingling demand deposits and lending.
What happens to the existing banks? They restructure into a banking subsidiary managing deposits and an investment manager running mutual funds, (because in the next step we kill money market funds!)
Third, eliminate money market fund pricing exemptions
Money market funds exist to deceive the public. I'm not overstating this in any way. If we remove the exemptions that allow money market funds to manipulate their net asset values so they look riskless, then the public will understand that bank deposits (in a 100% reserve bank) have no risk, but that money market fund's share price bounces around a little because it is risky. The money market fund is pretty darn available for withdrawal, but the price moves.
Under these circumstances, the saving and investing public makes clear distinctions between storing money in a way that is always available (saving), and lending money for risk taking purposes (investing.)
I suspect this third step would be the end of money market funds. Money market funds would become ultra short term bond funds...because that's what they are without the regulations designed to deceive us. At that point, however, there would be no reason NOT to let them fail. You, the investor took a risk. Too bad. You had an alternative.
Monday, April 13, 2015
Malcolm Forgot Who Stands In The Middle: Why American Taxpayers Don't Cheat
Malcolm Galdwell hit the Sunday TV circuit this week in preparation for dreaded Tax Day. In this video from CNN, he reiterates his standard trope about legitimacy. He tells us that cheating on our income taxes carries little risk because the IRS audits so few, and the penalties lack teeth. But, we pay anyway because we think the system is legitimate.
Gladwell needs to read some economics. Seriously. Tirole. Milgrom. Holstrom. Something on principal agent problems?!? Unless you follow the Wesley Snipes strategy and just don't pay, (which lands you in jail,) cheating on your taxes is pretty darn hard.
The United States taxpayer faces a uniquely complex, arcane and ridiculous system. Gladwell has that one right. Knowing little about the (vast number of) readers of this blog, I suspect only my mother prepares her taxes unassisted by anything more than IRS instruction documents and a sharp pencil. No software. No accountant.
Even minor complications cause the average American to toss her hands up and hire a professional. Given the vast sums spent advertising by low cost tax prep companies, I'd imagine the vast majority of even "simple" returns have professional help.
(Yes, refund anticipation loans may drive the profits of these shops, but that tells us people have decided that the value of the loan is worth more than the expected value of their ability to cheat successfully.)
So, why is Gladwell delusional? He ignores the principal-agent problem the tax code manufactures. We Americans cannot file our own taxes. Therefore, we cannot cheat without a colluding professional. That professional's entire career depends on a working relationship with the IRS. Your tax gal will not let you cheat. She monitors you, on behalf of the IRS. And, for this you willingly pay her!
An early Happy April 15!
Gladwell needs to read some economics. Seriously. Tirole. Milgrom. Holstrom. Something on principal agent problems?!? Unless you follow the Wesley Snipes strategy and just don't pay, (which lands you in jail,) cheating on your taxes is pretty darn hard.
The United States taxpayer faces a uniquely complex, arcane and ridiculous system. Gladwell has that one right. Knowing little about the (vast number of) readers of this blog, I suspect only my mother prepares her taxes unassisted by anything more than IRS instruction documents and a sharp pencil. No software. No accountant.
Even minor complications cause the average American to toss her hands up and hire a professional. Given the vast sums spent advertising by low cost tax prep companies, I'd imagine the vast majority of even "simple" returns have professional help.
(Yes, refund anticipation loans may drive the profits of these shops, but that tells us people have decided that the value of the loan is worth more than the expected value of their ability to cheat successfully.)
So, why is Gladwell delusional? He ignores the principal-agent problem the tax code manufactures. We Americans cannot file our own taxes. Therefore, we cannot cheat without a colluding professional. That professional's entire career depends on a working relationship with the IRS. Your tax gal will not let you cheat. She monitors you, on behalf of the IRS. And, for this you willingly pay her!
An early Happy April 15!
Monday, February 9, 2015
Sam Peltzman on World Cup Skiing
That's Bode Miller last week in Beaver Creek, CO, not me. Looks like he could use an airbag. The thing is, skiing airbags exist, but no one will wear one.
In this New York Times story, Marco Sullivan, U.S. Olympic skier notes "If you're the only guy wearing it, it's probably a disadvantage as far as speed goes." In fact, the author notes less than a second separated gold from 12th place. Six one-hundredths of a second separated gold from silver.
Sam Peltzman earned his fame demonstrating that seat belts made drivers faster and more reckless. They compensate for their increased safety.
I am far from a skiing expert, but I have to imagine that the marginally faster/more reckless skiing due to wearing the airbag more than makes up for the weight differential, and just might make up for that 0.06 seconds for second place.
In this New York Times story, Marco Sullivan, U.S. Olympic skier notes "If you're the only guy wearing it, it's probably a disadvantage as far as speed goes." In fact, the author notes less than a second separated gold from 12th place. Six one-hundredths of a second separated gold from silver.
Sam Peltzman earned his fame demonstrating that seat belts made drivers faster and more reckless. They compensate for their increased safety.
I am far from a skiing expert, but I have to imagine that the marginally faster/more reckless skiing due to wearing the airbag more than makes up for the weight differential, and just might make up for that 0.06 seconds for second place.
Thursday, May 29, 2014
The Ultimate Short Volatility Trade
My mother-in-law has a magic nose. She diagnosed a gas leak in our main feed into the house in 2009 that the "electronic nose" the PSE&G guy carries took an hour to find. So, when she arrived tonight and announced she smelled gas, I called the emergency hotline.
Tuesday, April 22, 2014
Flash Bubbes: An Ebay Revolt
My mother-in-law (or Bubbe, to my kids,) takes ebay very seriously. Anyone in the family needing to sell must run the gauntlet for her to consider risking her reputation on an item. She won't let you photograph it yourself. She won't let you ship it yourself. But, if you sell with her username, you have instant credibility.
However, when it comes time to buy, what does she advise? Turn to Michael Lewis' villains, the high frequency traders. The guys who throw massive computing power and light speed technology at their trades. She never buys without a "sniper"--that's ebay lingo for a high frequency trading operation. You tell them your limit price. They take care of the bidding. They place orders for you, at the tail end of auctions. The more you pay, the longer they'll wait. They virtually guarantee shaving a few bucks off that singing fish.
Friday, February 7, 2014
Doctor Sends Economist To ER With Heart Attack!
In this Op-Ed in the New York Times, Robert Hoffman of NYU's Langone Center writes in support of easy access to Naloxone, the antidote to heroin overdose. I'm inclined to agree with him, but his argument relies not on data, but on reductio ad absurdum, and the something isn't absurd.
Specifically, he writes:
I can almost guarantee Naloxone availability will lead to more heroine overdoses, but that's no longer fatal, so who cares? Will Naloxone lead to more heroine use? Two issues here:
Will a current heroin user consume more? Probably...the price of over-consumption drops dramatically from "death" to "nasal spray". But, that's the point! Hoffman wants to protect those consumers of heroin from accidental death.
Will non-heroin users become users? I have not used heroin. I cannot say my risk of death from overdose has ever crossed my mind. Is that risk what stops you from using heroin?
Specifically, he writes:
Some people might argue that the widespread distribution of a safe, effective and inexpensive antidote might actually encourage drug use. But that’s like suggesting that air bags and seatbelts encourage unsafe driving. Naloxone is a public-health method of intervening when a life is in the balance. Its distribution is endorsed by the American Medical Association. (emphasis added.)But, as ANY economist will tell you Sam Peltzman is famous for the way he dresses and demonstrating that seatbelts encourage unsafe behavior!! As I too often say...you want safe cab drivers in New York City? Replace the driver's airbag with an ice pick.
I can almost guarantee Naloxone availability will lead to more heroine overdoses, but that's no longer fatal, so who cares? Will Naloxone lead to more heroine use? Two issues here:
Will a current heroin user consume more? Probably...the price of over-consumption drops dramatically from "death" to "nasal spray". But, that's the point! Hoffman wants to protect those consumers of heroin from accidental death.
Will non-heroin users become users? I have not used heroin. I cannot say my risk of death from overdose has ever crossed my mind. Is that risk what stops you from using heroin?
Monday, October 28, 2013
Gay Couples? What Are The Odds?
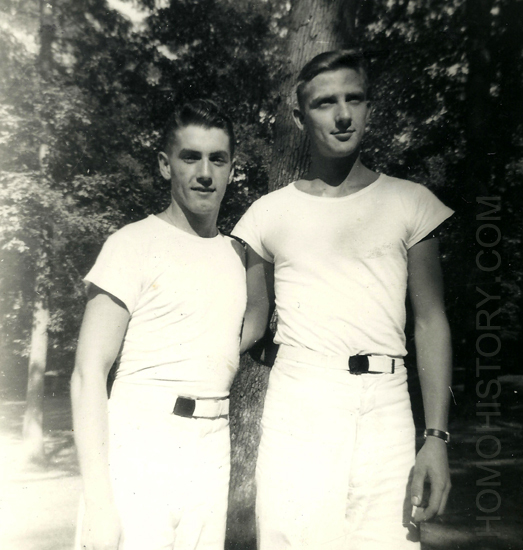
In this Huffington Post piece, an antique photograph collector explains that he believes he has a special collection of photographs of gay couples from bygone days. He even blogs about it, but I won't include the link because it doesn't seem to work.
Jeffery Gent is passionate about what he does. The article quotes him saying "Unfortunately, so many of these photos were purposely destroyed by horrified family members..." He continues "For every photo that I may have mistakenly identified as gay, thousands more were burned or torn into pieces to keep a family secret..."
To those who hated college statistics, it may not be obvious that we can examine this one pretty easily. To those of you who hated college statistics and passed the class, remember, you performed no worse than I did. (D in undergrad stats. You can only imagine what now Nobel Prize winning Lars Hansen, my dissertation adviser, said when he learned this.)
We'll attempt to apply Bayes Law to see what we might know about the probability that anyone in these images is gay. Bayes Law is a great tool for drawing statistical inferences.
Where do we start?I'll formulate an answer so you can easily play with a Bayesian calculator on your own.
What is our hypothesis? The image shown portrays two gay men.
What is the data? The data is a picture of two men.
We want to know, conditional on the existence of a photograph, the probability that the picture depicts two gay men.
What is the unconditional probability an image of two men is of gay men? This is somewhat arbitrary (and political, potentially.) So, let's say 20%. It doesn't matter much. We could say that number is high (or low) for the total population of men. We could say that number is low (why do two straight guys get photographed together?) We could say that number is high (Don't many brothers appear in photographs together? Grooms and best men?)
The key, really, is the the claim by Gent that most photographs of known gay couples were destroyed by family and friends out of a desire for secrecy.
Images are gone for two reasons: Passive loss (accidental disposal, fire, time) and active loss ("We're small minded, bigoted people who are ashamed, so we are destroying his memory.")
We need to establish the probability that a picture exists today conditional on straight men in it, and the probability that pictures exist today conditional on gay men in it.
Suppose 50% of all images are lost passively, but that a further 25% of gay men images are lost actively. This is incredibly conservative based on Gent's statement. We're saying only 50% of known gay images are destroyed actively. He's implying the vast majority.
So, in our calculator, we have Pr(Image Exists | Gay) = 0.25 and Pr(Image Exists | Not Gay) = .5.
What's the result? Pr(Gay | Image Exists) is about 11%.
If the vast majority of images depicting known gay men were destroyed (a la Gent) and we set Pr(Image Exists | Gay) = 0.01, then it is virtually impossible that any of the images depict gay men.
Even if most of the images taken historically were of gay men (90%) and the spiteful relatives destroyed 99% of them, it remains the case that only 15% of surviving images depict gay men.
Nice collection of old pictures, though.
Jeffery Gent is passionate about what he does. The article quotes him saying "Unfortunately, so many of these photos were purposely destroyed by horrified family members..." He continues "For every photo that I may have mistakenly identified as gay, thousands more were burned or torn into pieces to keep a family secret..."
To those who hated college statistics, it may not be obvious that we can examine this one pretty easily. To those of you who hated college statistics and passed the class, remember, you performed no worse than I did. (D in undergrad stats. You can only imagine what now Nobel Prize winning Lars Hansen, my dissertation adviser, said when he learned this.)
We'll attempt to apply Bayes Law to see what we might know about the probability that anyone in these images is gay. Bayes Law is a great tool for drawing statistical inferences.
Where do we start?I'll formulate an answer so you can easily play with a Bayesian calculator on your own.
What is our hypothesis? The image shown portrays two gay men.
What is the data? The data is a picture of two men.
We want to know, conditional on the existence of a photograph, the probability that the picture depicts two gay men.
What is the unconditional probability an image of two men is of gay men? This is somewhat arbitrary (and political, potentially.) So, let's say 20%. It doesn't matter much. We could say that number is high (or low) for the total population of men. We could say that number is low (why do two straight guys get photographed together?) We could say that number is high (Don't many brothers appear in photographs together? Grooms and best men?)
The key, really, is the the claim by Gent that most photographs of known gay couples were destroyed by family and friends out of a desire for secrecy.
Images are gone for two reasons: Passive loss (accidental disposal, fire, time) and active loss ("We're small minded, bigoted people who are ashamed, so we are destroying his memory.")
We need to establish the probability that a picture exists today conditional on straight men in it, and the probability that pictures exist today conditional on gay men in it.
Suppose 50% of all images are lost passively, but that a further 25% of gay men images are lost actively. This is incredibly conservative based on Gent's statement. We're saying only 50% of known gay images are destroyed actively. He's implying the vast majority.
So, in our calculator, we have Pr(Image Exists | Gay) = 0.25 and Pr(Image Exists | Not Gay) = .5.
What's the result? Pr(Gay | Image Exists) is about 11%.
If the vast majority of images depicting known gay men were destroyed (a la Gent) and we set Pr(Image Exists | Gay) = 0.01, then it is virtually impossible that any of the images depict gay men.
Even if most of the images taken historically were of gay men (90%) and the spiteful relatives destroyed 99% of them, it remains the case that only 15% of surviving images depict gay men.
Nice collection of old pictures, though.
Wednesday, October 23, 2013
Oregon Taxpayers, Please Meet Michael Dell
Should public universities go private? It's a hot topic in Oregon. Three of their seven public universities "go private" next year.
Of course I'm in favor of most anything going private, but let's consider this from the view of the Oregon taxpayer, the likely loser here.
A public university going private sounds an awful lot like Michael Dell leading a private equity buyout of the public company he founded. Substitute faculty and administration for buyout firm and Michael Dell. Substitute Oregon for the selling shareholders.
Since no one has asked, I will offer my "fairness opinion" on this buyout transaction: Good luck making this fair. The state of Oregon contributed land, taxing authority, governance, pension backstops, and I don't know what else, to this enterprise. Now, the new management team wants to take all that in the interests of better education, when the only obvious plans are more generous salaries and benefits, combined with higher top-line tuition. That sounds great already.
How about this: Let the universities go private. Let them raise capital to fund an endowment, (remember a hedge fund that prints diplomas doesn't pay taxes!) Buy the assets from the state university system: dorms, lecture halls, football stadiums...don't forget the goodwill. Also, make sure they can fund healthcare and retirement benefits without using state resources.
Sounds impossible right? I guess that's why those who run the University of Phoenix aren't running around buying up universities, huh?
Of course I'm in favor of most anything going private, but let's consider this from the view of the Oregon taxpayer, the likely loser here.
A public university going private sounds an awful lot like Michael Dell leading a private equity buyout of the public company he founded. Substitute faculty and administration for buyout firm and Michael Dell. Substitute Oregon for the selling shareholders.
Since no one has asked, I will offer my "fairness opinion" on this buyout transaction: Good luck making this fair. The state of Oregon contributed land, taxing authority, governance, pension backstops, and I don't know what else, to this enterprise. Now, the new management team wants to take all that in the interests of better education, when the only obvious plans are more generous salaries and benefits, combined with higher top-line tuition. That sounds great already.
How about this: Let the universities go private. Let them raise capital to fund an endowment, (remember a hedge fund that prints diplomas doesn't pay taxes!) Buy the assets from the state university system: dorms, lecture halls, football stadiums...don't forget the goodwill. Also, make sure they can fund healthcare and retirement benefits without using state resources.
Sounds impossible right? I guess that's why those who run the University of Phoenix aren't running around buying up universities, huh?
Monday, May 6, 2013
Another Bad Reason To Invest In Hedge Funds
I know, we need bad arguments for hedge fund investing like we need...bad advice from big banks?
In an May 2nd "Eye on the Market" piece from J. P. Morgan's Private Bank, Michael Cembalest suggests that investing in hedge funds in a low yield/low spread/low everything environment might be an interesting idea. He bases this argument on this very pretty picture:
This picture shows the annualized performance of randomly generated portfolios of five hedge funds that happen to have a ten year history. Cembalest argues that because the volatility of these portfolios apparently falls below the volatility of BBB bonds, and the returns fall pretty reliably in the 4%-7% range, this might be a good time to invest in smartly constructed portfolios of hedge funds.
Here's the thing: Hedge fund managers trade spreads, they don't perform alchemy.
So-called "arbitrage" strategies earn a spread over cash returns! The annualized return on three month Treasury Bills over this period plotted above is about 3.1%. So, at least we should knock 3.1% off the annualized returns because even hedge fund managers aren't making that return in today's environment.
Now, 1% - 4% returns with slightly lower than BBB corporate volatility doesn't look as good anymore, does it?
I guess we should rethink randomly picking portfolios of hedge funds.
P.S. Yes, I should recalculate the vol measures as spreads too.
P.P.S. You disagree that hedge fund managers earn spreads over cash? Please send me an example. I probably disagree!
In an May 2nd "Eye on the Market" piece from J. P. Morgan's Private Bank, Michael Cembalest suggests that investing in hedge funds in a low yield/low spread/low everything environment might be an interesting idea. He bases this argument on this very pretty picture:
This picture shows the annualized performance of randomly generated portfolios of five hedge funds that happen to have a ten year history. Cembalest argues that because the volatility of these portfolios apparently falls below the volatility of BBB bonds, and the returns fall pretty reliably in the 4%-7% range, this might be a good time to invest in smartly constructed portfolios of hedge funds.
Here's the thing: Hedge fund managers trade spreads, they don't perform alchemy.
So-called "arbitrage" strategies earn a spread over cash returns! The annualized return on three month Treasury Bills over this period plotted above is about 3.1%. So, at least we should knock 3.1% off the annualized returns because even hedge fund managers aren't making that return in today's environment.
Now, 1% - 4% returns with slightly lower than BBB corporate volatility doesn't look as good anymore, does it?
I guess we should rethink randomly picking portfolios of hedge funds.
P.S. Yes, I should recalculate the vol measures as spreads too.
P.P.S. You disagree that hedge fund managers earn spreads over cash? Please send me an example. I probably disagree!
Wednesday, March 13, 2013
Conflicts and College Savings...and Brookings Fellow Proposes Zero Taxes on Savings!!
Suppose I worked for Harvard, and I wrote that the education crisis in America had reached new levels, and that the federal government needed to act now(!) to help people realize the American Dream of going to college because, it's in the public interest, after all, people with a college education have far lower unemployment than those without, and our nation benefits.
You'd call me a hero, right?
Or, would you cry foul because I'm the direct beneficiary of such Federal Government largess?
| Robert Pozen, courtesy of Harvard |
That's exactly what's going on over at Yahoo!, in a piece written by Robert Pozen, a lecturer at Harvard, and senior fellow at Brookings.
First, he proposes that the U.S. Department of Education should take a more active role in marketing 529 Plans, the tax protected investment vehicles used to save for college. In other words, the U.S. government should work harder to sell you mutual funds destined to pay his salary. Second, he wants unused balances in 529 Plans to convert to IRAs, traditional retirement savings vehicles.
Three years ago, I wrote we should do away with 529 plans. They're a terrible waste of resources, that even Pozen acknowledges only benefit wealthy people. They also subsidize Pozen and his colleagues because they lessen the real impact of tuition increases.
But Pozen wants you to have the added benefit of the IRA conversion if your child doesn't go to college. That sounds good, right? Of course the reason people who are saving for neither college nor retirement is that they're worried they'll have too much saved for college! What??
In fact, Pozen's proposal is the greatest tax break for the wealthy in the history of...well, in the history of the Brookings Institution!
Here's a secret: All you need to sock away $250,000 tax free in a 529 Plan is the social security number of the beneficiary. You don't need to tell the beneficiary. You don't need to tell the parents. The IRS doesn't care. No limit on the number of kids. You can play shell games with the beneficiaries, as long as they're first cousins. By Pozen's proposal, one of those first cousins doesn't go to college and PRESTO! one giant IRA. Take that, IRS!
If Pozen gets his way, here's my advice to the extremely wealthy: Find yourself a nice, large Hasidic Jewish family, and pretend you're the rich grandparent! You could easily have 50 or more first cousins, and chances are someone isn't going to college.
Thursday, January 10, 2013
It's Only Money
I have a secret for you: U.S. dollars aren't really worth anything. It's magic. Economists call it fiat money.
You already knew this. You don't like thinking about it. The debt ceiling debate makes you acknowledge our currency has no value.
| From TPM.com via Krugman at NYT |
In this Op-Ed in the New York Times, Edward Kleinbard suggests the Treasury adopt the solution California used when they ran out of money: Issue scrip. He writes:
To avoid any confusion with actual Treasury debt, and to be consistent with the law governing claims against the United States more generally, the scrip would not pay interest in most cases. And unlike debt, it would have no fixed maturity date but rather would become redeemable in cash only when the secretary of the Treasury was able to certify that there’s enough money available in the Treasury’s general fund to cover it.
Did you read that carefully? Kleinbard defines "scrip" as pieces of paper with serial numbers that change hands freely, and do not bear interest. Guess what: That's fiat money!Finally, the scrip would be transferable, allowing financial institutions to buy it at a high percentage of its face value, knowing that the political crisis would almost certainly be resolved before long.
[Yes, California issued its own currency in 2011, in theory backed by U.S. currency, which is backed by air...but only in theory.]
Sunday, December 30, 2012
The Grinch Who Mispriced Volatility
In my very first post, I hit on the annual ritual of Grinch economists explaining the inefficiencies of Christmas (and other) gift giving, and my personal disgust with the concomitant trade in gift cards instead of cash. (That's my second post this week using the word "concomitant", by the way!)
I even confessed to my personal failure to adequately monitor my accumulated gift card credit risk following the Border's bankruptcy.
In a beautifully titled piece How Terrible Is Christmas? Megan McCardle proposes two arguments in favor of inefficient giving, giving a slightly less Grinch-y approach to economic analysis of gift giving. Unfortunately, her arguments don't hold up.
First, she argues, building social networks requires inefficient allocation of resources. Short term, seemingly irrational, commitments of time, money and effort shows commitments to new, long term relationships. That makes sense.
However, most Christmas gift-giving focuses on existing relationships, not building new ones. She turns to her own grandmother as an example, but grandmothers cannot buy long term relationships.
In fact, I'd guess Christmas gift-giving etiquette tends toward much more modest gifts for new relationships, to specifically avoid the risk of "over-commitment" to new relationships.
I even confessed to my personal failure to adequately monitor my accumulated gift card credit risk following the Border's bankruptcy.
In a beautifully titled piece How Terrible Is Christmas? Megan McCardle proposes two arguments in favor of inefficient giving, giving a slightly less Grinch-y approach to economic analysis of gift giving. Unfortunately, her arguments don't hold up.
First, she argues, building social networks requires inefficient allocation of resources. Short term, seemingly irrational, commitments of time, money and effort shows commitments to new, long term relationships. That makes sense.
However, most Christmas gift-giving focuses on existing relationships, not building new ones. She turns to her own grandmother as an example, but grandmothers cannot buy long term relationships.
In fact, I'd guess Christmas gift-giving etiquette tends toward much more modest gifts for new relationships, to specifically avoid the risk of "over-commitment" to new relationships.
Thursday, December 27, 2012
Weekend at Bernie's III
Bernie Madoff has a lot to say about insider trading and other fun stuff. In his year end letter (hmm...even jailed, fund-less hedge fund managers write them...how quaint!) Madoff expresses concerns over dark pools, high frequency trading and concomitant insider trading. I have concerns too, but not for the same reasons.

Madoff explains that dark pools obscure information (that's good...that's what smart buyers and sellers do,) fast execution prevents leakage of information (that's good too!) but leakage inevitably happens. This leakage, he tags as insider trading.
[Side note: This insider trading argument about leakage is complicated stuff! Maybe this set of rules helps you understand. If your information is bad and it leaks, you are dumb money being outsmarted. If your information is irrelevant but your trades leak, you're being front run. If your information is good and your trade leaks, you are insider trading. Got that?]
Is information leakage really insider information? Of course not! Why is anyone interested in the financial market prognostications of a convicted felon who completely failed to successfully manage anyone's money??
Madoff explains that dark pools obscure information (that's good...that's what smart buyers and sellers do,) fast execution prevents leakage of information (that's good too!) but leakage inevitably happens. This leakage, he tags as insider trading.
[Side note: This insider trading argument about leakage is complicated stuff! Maybe this set of rules helps you understand. If your information is bad and it leaks, you are dumb money being outsmarted. If your information is irrelevant but your trades leak, you're being front run. If your information is good and your trade leaks, you are insider trading. Got that?]
Is information leakage really insider information? Of course not! Why is anyone interested in the financial market prognostications of a convicted felon who completely failed to successfully manage anyone's money??
Wednesday, December 26, 2012
The New University
As a PhD student, I didn't understand MBAs. To me, business school looked like a series of cocktail parties and social events combined with a couple of good finance classes, as a reward for passing rigorous admissions criteria, throwing away two years and a lot of cash. The efficient outcome should have been admissions teams providing signals of approval, combined with cocktail parties, networking, much higher fees and less time away from work. Hence, we now have executive MBAs!
So, with my stellar, self-proclaimed track record, I'm making five new education predictions in honor of the new year!
- Accredited credit aggregation. Some established university will realize they can outsource so much of their course materials to high quality, low cost, online providers that the role of the school will become evaluating the quality of third party provided education, in effect aggregating credits earned somewhere else.
- University as group home. Colleges and universities have become resorts. On campus education has lost relevance for students. Social life still matters. Kids still want to live in dorms, away from their parents. And they don't want to cook. Classrooms will have limited use. Research facilities will be privatized and/or separated from the core of the "school". Thw dorms, dining halls, student centers and gymnasiums will transform into year round moderately priced residences for young adults.
- Extreme specialization. Endowments at most universities cannot support a broad range of programs. Even those most skeptical of online education will realize that good online courses have greater value than mediocre classroom instruction. Schools will only teach locally the subjects in which they have absolute advantage, or minimally the threshold for comparative advantage will rise dramatically...and cost will matter.
- Merger wave. After hurricane Katrina, I suggested Harvard should have bought Tulane. Carnegie Mellon has 16 listed degree granting programs not in Pittsburgh. Why should academic departments of a single university be anywhere near each other? MIT wants humanities? Buy William College.
- Privatization via globalization. Beyond selling off the research facilities, leaving campuses as non-profit housing operations, maybe even becoming for profit residential REITs, some university will re-brand, i.e. sell itself, to a foreign university. How can we "solve" the University of California funding crisis? Sell off several campuses as the U.S. base of Chinese universities.
Thursday, December 13, 2012
God Save These United States!
In case you've been under a rock, the fiscal cliff approaches. What's our government doing, meanwhile?
What could possibly top Bernie Sanders, the great Senator from Vermont, killing 8 hours, 37 minutes of senate floor time on a tirade?
How about Missouri Republican Blaine Luetkemeyer's (pictured here) ground breaking legislation introduced today, HR 5817, which proposes to relax the law that requires your financial institutions send you a privacy statement in the mail once a year that says they share your data with whomever the hell they'd like? He figures it's a waste of paper. I agree. Maybe that even makes him an environmentalist.
Doesn't he realize those privacy statements keep the Post Office afloat?
That's the answer! A special tax on banks to fill the budget hole at the Post Office!
Maybe tomorrow someone will do something useful...
What could possibly top Bernie Sanders, the great Senator from Vermont, killing 8 hours, 37 minutes of senate floor time on a tirade?
How about Missouri Republican Blaine Luetkemeyer's (pictured here) ground breaking legislation introduced today, HR 5817, which proposes to relax the law that requires your financial institutions send you a privacy statement in the mail once a year that says they share your data with whomever the hell they'd like? He figures it's a waste of paper. I agree. Maybe that even makes him an environmentalist.
Doesn't he realize those privacy statements keep the Post Office afloat?
That's the answer! A special tax on banks to fill the budget hole at the Post Office!
Maybe tomorrow someone will do something useful...
Monday, December 10, 2012
How Much Is That Free Latte?
Please read this Op-Ed from the New York Times. If you're in too much of a hurry, it reminds us all of the absurdity of the terms and conditions we accept every day. Companies ask us to throw away our rights left, right and center every time we do business with them.
So, I actually read the Panera Bread terms and conditions for the MyPanera discount card this morning, before heading out to lunch. Here's the best part:
I'm passing on the latte...and not just because I don't drink coffee!
So, I actually read the Panera Bread terms and conditions for the MyPanera discount card this morning, before heading out to lunch. Here's the best part:
In the event that Panera, its affiliates, our/their franchisees, and/or suppliers are found liable to you for any reason, you shall only be entitled to recover actual and direct damages and such damages shall not exceed $100.That's right, $100 limit no matter what happens to you, no matter what Panera (or its affiliates!) may have done wrong.
I'm passing on the latte...and not just because I don't drink coffee!
Tuesday, December 4, 2012
Economic Irony
According to this story, the investment committee that oversees the assets backing the Nobel Prizes has decided that they need to invest in more hedge funds!
Did they read any of the research behind the prizes in economics??
Sunday, December 2, 2012
Jeffersonian Economics?
Struck by the confidence and clarity of this Op-Ed piece in the New York Times (for simplicity, Finkelman argues that Jefferson was a deeply racist man,) I had to compare the Thomas Jefferson Foundation's Monticello web site official statements on Jefferson and slavery, (which treats the matter of his slaves very "delicately" to say the least.)
Two entirely incontrovertible statements: Jefferson owned lots of slaves. Jefferson was a brilliant thinker.
Armed with these two statements, and some basic facts from the Thomas Jefferson Foundation, what could anyone with a basic understanding of economics conclude?
Question 1: Did Jefferson have a basic understanding of economics?
Rather than simply saying "he was a really smart guy who knew most things", we can point to the official Monticello statements again:
Two entirely incontrovertible statements: Jefferson owned lots of slaves. Jefferson was a brilliant thinker.
Armed with these two statements, and some basic facts from the Thomas Jefferson Foundation, what could anyone with a basic understanding of economics conclude?
Question 1: Did Jefferson have a basic understanding of economics?
Rather than simply saying "he was a really smart guy who knew most things", we can point to the official Monticello statements again:
"I consider a woman who brings a child every two years as more profitable than the best man of the farm," Jefferson remarked in 1820. "What she produces is an addition to the capital, while his labors disappear in mere consumption."
So, in 1820 Jefferson clearly understood that "his" capital stock grew naturally, and this drove its value. For a farmer, or anyone who raises animals, this is obvious. Female cattle have far greater value than male cattle. People have known this since ancient times. (Why else would virtually all animal sacrifices in ancient times call for males of the species!)
Sunday, November 25, 2012
Sandy, Part 4: Economics 101, New Jersey Style!
In Sandy, Part 2 I noted that restrictions on post-catastrophe price gouging forced consumers to trade gasoline in time instead of dollars. This resulted in many lost hours, as consumers waited in long lines, and wealthy gas guzzlers bought gas from their neighbors long on time and short on cash.
I proposed an elegant solution: Gasoline backed contingent claims, freely tradeable, but only usable after the governor declares an emergency. Governor Christie hasn't called for my help. However, his colleague from Parsippany, BettyLou DeCroce, has proposed her own solution: The government should price gouge the gas stations instead!
That's economics New Jersey style! DeCroce sponsored the New Jersey Residents Power Protection Act that would require gas station owners to buy generators that would power their operations for 72 hours or more.
The legislation also applies to all new grocery stores and convenience stores. (Gee, what about Starbucks? Oil refineries? Why not DeCroce's house?? I know how she's getting re-elected!)
Just for good measure, she says generators must use natural gas to ensure uninterrupted, safer and cleaner power supplies. (Yes, the gasoline station must use natural gas to power its generators because gasoline could be difficult to obtain, and gasoline is dangerous. It's no wonder we don't have self serve gas in New Jersey because it's unsafe!)
Here's an idea for our fearless politicians to consider: Let gas stations that want to install generators install them. Then, let them charge more for gasoline after a catastrophe to recover the cost of the generator.
Oh, but that's price gouging.
I proposed an elegant solution: Gasoline backed contingent claims, freely tradeable, but only usable after the governor declares an emergency. Governor Christie hasn't called for my help. However, his colleague from Parsippany, BettyLou DeCroce, has proposed her own solution: The government should price gouge the gas stations instead!
That's economics New Jersey style! DeCroce sponsored the New Jersey Residents Power Protection Act that would require gas station owners to buy generators that would power their operations for 72 hours or more.
The legislation also applies to all new grocery stores and convenience stores. (Gee, what about Starbucks? Oil refineries? Why not DeCroce's house?? I know how she's getting re-elected!)
Just for good measure, she says generators must use natural gas to ensure uninterrupted, safer and cleaner power supplies. (Yes, the gasoline station must use natural gas to power its generators because gasoline could be difficult to obtain, and gasoline is dangerous. It's no wonder we don't have self serve gas in New Jersey because it's unsafe!)
Here's an idea for our fearless politicians to consider: Let gas stations that want to install generators install them. Then, let them charge more for gasoline after a catastrophe to recover the cost of the generator.
Oh, but that's price gouging.
Subscribe to:
Posts (Atom)